HDB resale process for first-time buyers: your step-by-step guide
Buying or selling an HDB resale flat follows a fixed legal sequence, and skipping a step means starting over. Buyers need a valid HDB Flat Eligibility (HFE) letter, good for 6 months, before an Option to Purchase (OTP) can be granted. Sellers must register Intent to Sell at least a week before issuing that OTP, and the registration remains valid for about a year.
Once the OTP is exercised, the clock starts running hard. The second party has 7 days to submit their portion of the resale application or the whole thing lapses. Buyers using CPF savings or a loan must lodge a Request for Value with a $120 (GST inclusive) processing fee. HDB typically accepts a complete application within 28 working days, and completion usually follows about 8 weeks after that.
Before you go any further, check three things: your HFE letter status, the seller’s Intent to Sell timing, and whether your finances can absorb the resale levy, agent fees, and administrative charges on top of the flat price.
- HFE letter: apply early, valid for 6 months
- Intent to Sell: sellers register first, wait 7 days minimum before granting OTP
- OTP exercise: triggers the 7-day second-party submission deadline
- Request for Value: $120 fee, due by the next working day after the Option Date
- HDB acceptance: targeted within 28 working days
- Completion: roughly 8 weeks after acceptance
Quick fact: Miss the 7-day submission window after OTP exercise and your application lapses, with fees forfeited. There’s no grace period.
Key Takeaways
Completing an HDB resale successfully depends on meeting fixed deadlines, mainly the HFE letter, the Intent to Sell waiting period, and the 7-day submission windows, in the correct order.
| Point | Details |
|---|---|
| Get your HFE letter early | It’s valid for 6 months and must be in hand before any OTP is granted. |
| Respect the 7-day Intent to Sell wait | Sellers must wait 7 days after registration before granting an OTP. |
| Never miss the second submission | The second party has 7 days after OTP exercise or the application lapses. |
| Budget for fixed fees | Expect the $120 Request for Value fee plus administrative charges. |
| Get a valuation before you commit | Registertoday’s free home valuation helps estimate net proceeds ahead of your OTP decision. |
Table of Contents
- Step-by-step checklist: from HFE to resale completion
- Documents, payments and checks both buyer and seller must prepare
- Timelines and fees: what to plan for and when
- Common pitfalls and red flags that cause delays or rejection
- What happens at resale completion and practical steps for the day
- Registertoday’s practical perspective: reducing timing and paperwork risk
- How Registertoday helps you get through the resale process without the guesswork
- Sources
Step-by-step checklist: from HFE to resale completion
The HDB resale procedure runs in a strict order. Follow it in sequence and you avoid most of the delays that trip up first-time buyers.
- Seller registers Intent to Sell. This happens through the HDB Flat Portal and starts a mandatory 7-day countdown. No OTP can be issued during that window.
- Seller grants the OTP. It must be the HDB-prescribed form, complete with a unique serial number. The option fee (paid to secure the OTP) and the option exercise fee (paid when you exercise it) both count towards your deposit.
- Buyer submits Request for Value. If you’re using CPF savings or a housing loan, this is due by the next working day after the Option Date, with a non-refundable $120 fee attached.
- Both parties submit their resale application portions on My Flat Dashboard. This is a two-part process. Whoever exercises the OTP submits first; the other party has exactly 7 days to complete their half or the application lapses entirely.
Pro Tip: Assign one person, buyer or seller, as the point of contact for portal notifications during the submission window. Most lapsed applications happen because nobody was watching for the 7-day deadline.
Documents, payments and checks both buyer and seller must prepare
Getting your paperwork right the first time avoids a rejected application and a lost fee. Both parties need to gather specific items before submission, not after.
- Valid identity documents (NRIC) for every applicant named on the HFE letter or Intent to Sell
- A scanned copy of OTP page 1, including the serial number, matching exactly what’s recorded on the Intent to Sell and HFE letter
- Proof of tax and Service & Conservancy Charge (S&CC) payment from the seller
- Mortgage insurance proof where an HDB loan is involved
- CPF withdrawal statements confirming refund amounts owed back to your CPF account
Sellers should expect their sale proceeds to be reduced by any outstanding loan balance, CPF refund with accrued interest, and resale levy if a second subsidised flat was purchased previously. These deductions happen automatically at completion, not as a separate bill.
You’ll also need to decide on conveyancing. Most buyers and sellers use HDB’s own conveyancing service, though private solicitors remain an option for those wanting independent legal advice. If someone can’t attend to sign in person, a Power of Attorney needs to be arranged and lodged well ahead of the completion date.
Timelines and fees: what to plan for and when
The Registertoday resale checklist below is worth keeping close at hand, because most of these deadlines are non-negotiable and none of them offer a grace period.
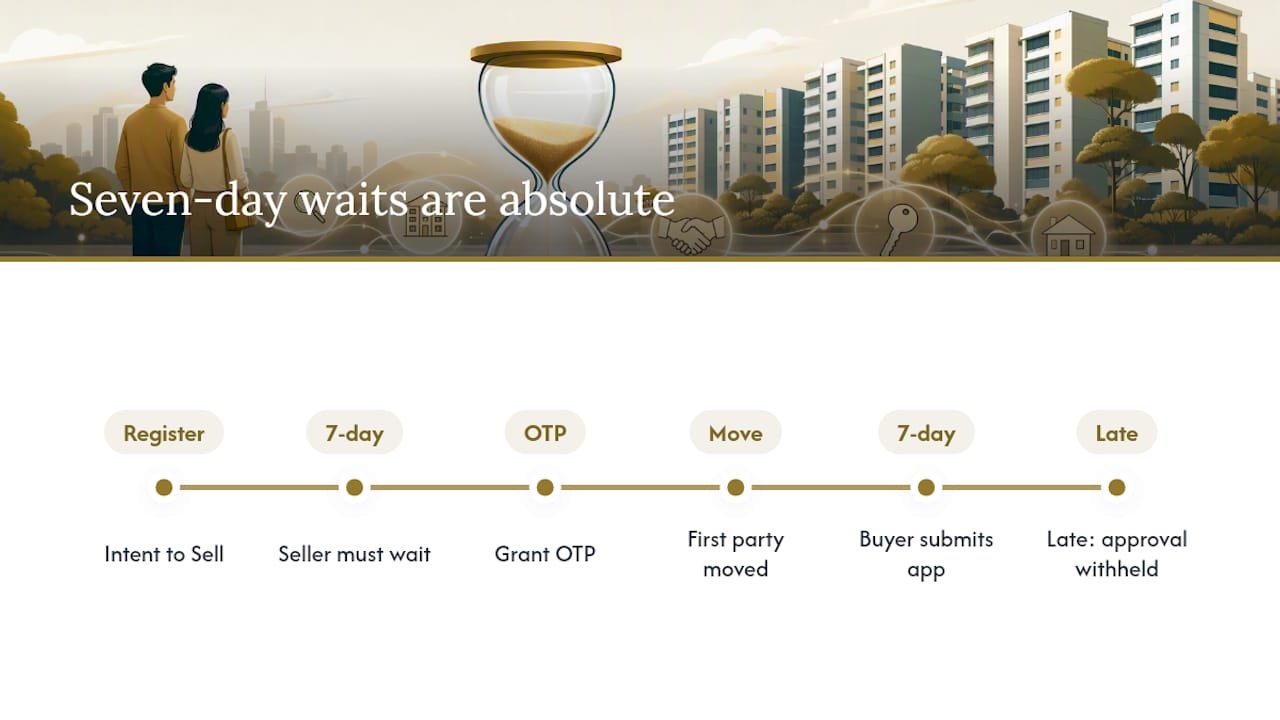
The two rules most first-time buyers underestimate are the 7-day windows. One governs how long a seller must wait after registering Intent to Sell before granting an OTP. The other governs how quickly the second party must submit their resale application portion once the first party has moved. Both are absolute, and HDB’s own procedures treat late endorsement or payment as grounds to withhold approval.
Common pitfalls and red flags that cause delays or rejection
Most rejected or lapsed applications trace back to a handful of avoidable mistakes.
- Mismatched details. Names, NRIC numbers, or household composition that don’t match across the HFE letter, Intent to Sell, and resale application will flag your submission for review.
- Late or unpaid Request for Value. Miss the next-working-day deadline and you risk delaying the entire timeline, since CPF and loan disbursement depends on it.
- Amended OTPs or side agreements. Any attempt to alter the declared price or add a private side letter is void under the Housing and Development Act, full stop.
- Ignoring portal notifications. Documents and payments must be endorsed through the HDB Flat Portal within the timeframes given, or your approval can be withheld.
Pro Tip: Set a calendar reminder for every deadline the moment your OTP is exercised. The 7-day windows move fast, and HDB’s portal doesn’t send a second warning.
What happens at resale completion and practical steps for the day
Completion is where ownership formally changes hands, and both sides need specific paperwork on the day.
- Sellers bring the original OTP and proof of tax or S&CC payment.
- Buyers bring final payment receipts and, where an HDB loan is used, a valid Certificate of Insurance for Mortgage Fire Insurance, since buyers using an HDB loan must show this at completion.
- Both parties sign transfer and mortgage instruments; salespersons make statutory declarations where required.
- Keys change hands once all documents are endorsed.
If the seller needs more time in the flat, an extension of stay can be arranged, but it must be agreed before completion, not on the day. Failing to attend without prior arrangement can delay or jeopardise the entire transaction.
Registertoday’s practical perspective: reducing timing and paperwork risk
First-time buyers rarely lose money on the flat itself. They lose time, and sometimes fees, on missed deadlines. Registertoday works across Singapore’s resale market with ABSD-aware structuring, free valuations, and personalised negotiation support, backed by over $1 billion in completed sales.
What actually helps buyers isn’t more information, it’s someone tracking the 7-day windows alongside you and flagging a valuation gap before you commit to an OTP.
— Anderson
How Registertoday helps you get through the resale process without the guesswork
Registertoday is the alternative to going it alone on an HDB resale, giving first-time buyers a valuation and negotiation partner who tracks the deadlines with you instead of leaving you to monitor the portal solo.
The platform’s home valuation service gives you a realistic estimate of net proceeds before you commit to an Option to Purchase, which matters when resale levy and CPF refunds will reduce what actually lands in your account. Personalised negotiation support means you’re not working out ABSD implications or pricing gaps alone, and the coordination extends to timing the Request for Value and resale application submissions correctly.
If you’re ready to see what’s realistic for your budget, start with a home valuation or browse current resale listings to compare what’s on the market against your HFE eligibility.