Mortgage Broker vs Bank: Which Home Loan Route Suits You?
In Singapore, a mortgage broker compares packages across several banks and is usually paid by the bank you choose, while a bank adviser can only offer that bank’s own loans. Both routes are bound by the same Monetary Authority of Singapore (MAS) rules, so the real difference is breadth of choice, effort and how clearly the fee structure is explained to you, not whether you can borrow more.
TL;DR
- A bank offers only its own products. A broker compares packages from many banks and handles much of the paperwork.
- Brokers in Singapore are generally paid by the bank on loan disbursement, so you normally pay no direct fee. Ask for this in writing before you proceed.
- Neither route can bypass the 55% Total Debt Servicing Ratio (TDSR) or the Loan-to-Value (LTV) limits. Both are set by MAS and apply to every lender.
- Going direct suits borrowers with a strong existing relationship, a simple profile and time to compare. A broker suits those who want breadth and speed.
- Whichever route you take, read the Letter of Offer, and budget for mortgage duty, legal fees and the cash downpayment.
Table of Contents
- What actually differs between a broker and a bank
- What a bank offers when you go direct
- What a mortgage broker does
- How much does a mortgage broker cost?
- What neither route can change: TDSR and LTV
- Costs that do not depend on the route
- Fixed or floating: a question for both routes
- How to choose between them
- Our perspective
- Plan the property side before the loan
- FAQ
- Sources
What actually differs between a broker and a bank
The decision comes down to who you talk to, how many products they can show you, and how they are paid.
| Factor | Bank (direct) | Mortgage broker |
|---|---|---|
| Products shown | That bank’s own packages only | Packages from multiple banks |
| Who pays for the service | You, through the loan terms | Usually the bank, through a referral fee |
| Best for | Existing customers, simple cases | Comparing widely, tight timelines, complex income |
| Regulatory limits | MAS TDSR and LTV apply | The same MAS TDSR and LTV apply |
| Main risk | Seeing only a slice of the market | Advice shaped by which bank pays what |
MAS notes that banks must follow defined disclosure and affordability standards when pricing and revising residential mortgages. That protects you on both routes, but it does not make a single bank’s product the best one on the market.
What a bank offers when you go direct
When you walk into a branch or apply online, the officer works for that bank. They can explain its fixed and floating packages, lock-in periods and legal subsidies, and they often know your existing accounts, which can smooth the application. If you have a salary account, investments or a long history with the lender, that familiarity counts.
The limit is structural. A bank officer can only present their employer’s products. That is not dishonest, but it means you have no view of what the rest of the market offers unless you collect quotes yourself. Doing so across three or four banks is possible, but each one will ask for payslips, CPF contribution history, Notices of Assessment and your existing liabilities.
Going direct makes the most sense when:
- you already hold a strong relationship with the bank and have a clean, salaried income profile;
- you have the time to request and compare several written quotes yourself;
- the property and the loan are straightforward, such as a single owner-occupied purchase.
What a mortgage broker does
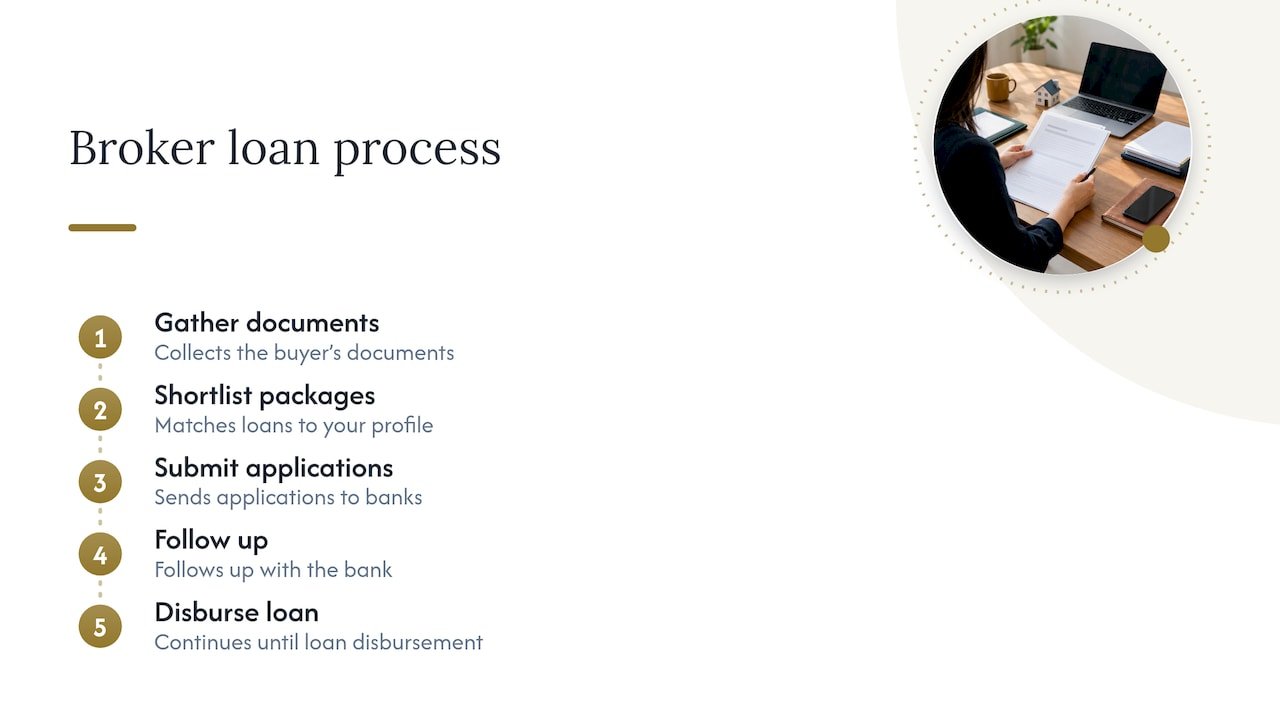
A broker is an intermediary. Experian describes the role as working with a broad range of lenders and matching you with a suitable loan, then guiding you through the paperwork. In Singapore this typically means the broker gathers your documents, shortlists packages that fit your profile, submits applications and follows up with the bank until the loan is disbursed.
The main advantage is breadth. A broker can show you which banks are more flexible on, for example, variable income, self-employment or a high existing commitment, which is hard to learn from one bank’s counter. For first-time buyers who do not know what to ask, that guidance can save weeks.
Brokers also help at the refinancing stage, when many homeowners revisit their loan once the lock-in ends. Our refinancing break-even checklist shows how to test whether a switch is worth the cost.
How much does a mortgage broker cost?
In Singapore, brokers are commonly paid by the lender. One Singapore industry guide states that the bank pays a referral fee when the loan is booked, so the comparison and advice are free to the borrower. A general overview of the role from NerdWallet also notes that borrower-paid fees can still arise in complex or specialised cases.
The practical rules are simple:
- Ask before you sign anything: “Will I pay you any fee, now or later?”
- Get the answer in writing, including what happens if you withdraw after approval.
- Ask which banks the broker works with, and whether the shortlist covers the whole market or only a few lenders.
- Ask whether the broker will also handle future refinancing, and on what terms.
A zero fee to you does not mean zero incentive. Because the bank pays, a broker could lean towards a lender with a higher payout. The way to check is to compare the broker’s recommended package with at least one quote you obtained yourself.
What neither route can change: TDSR and LTV
A common misunderstanding is that a broker can find a lender willing to lend more than the rules allow. They cannot. MAS sets rules for new housing loans that cover maximum loan tenure, loan-to-value ratio, mortgage servicing ratio and total debt servicing ratio, and every financial institution must apply them.
Two figures matter most:
- TDSR: your total monthly debt obligations, including the new mortgage, may not exceed 55% of your gross monthly income. MAS states this threshold has applied to new housing loans since 16 December 2021. See how it shapes your price band in our TDSR guide.
- LTV: the limit on how much of the property’s value a loan can cover. For a first housing loan from a financial institution it is typically 75%, with lower limits for later loans. Our LTV explainer sets out the tiers.
What a broker or bank can influence is the interest rate package, the lock-in, the subsidies and how your income is presented within the permitted rules. Lenders differ in how they assess variable income, and the general idea of lender serviceability tests is covered, from an Australian perspective, in this explainer on what lenders assess. Singapore’s formula is MAS-defined, but the principle that lenders examine your repayment capacity is the same.
Costs that do not depend on the route
First-time buyers often focus on the interest rate and overlook fixed costs. These apply whether a broker or a bank arranges the loan:
- Cash downpayment. The CPF Board explains that where the situation applies, 5% of the downpayment must be paid in cash, while the remaining 20% can use CPF savings. Check your own case on that page.
- Mortgage duty. IRAS publishes the mortgage duty rates payable on mortgage documents that secure a loan. Refinancing can trigger this duty again, so a switch is not cost-free.
- Legal and valuation fees. Lenders may subsidise some of these, but the subsidy often comes with a clawback if you redeem early. Read the clause.
For purchases still under construction, the timing of cash and loan drawdown also matters. Our guide to the progressive payment schedule walks through it.
Fixed or floating: a question for both routes
Bank officers and brokers alike will ask whether you prefer a fixed-rate package or one pegged to a floating benchmark such as SORA. This choice has more effect on your total interest than the broker-versus-bank decision itself. Before you compare packages, read the fact sheet for each one and check the same four points. Our fixed versus floating checklist lists them.
MAS also reminds borrowers that banks keep some discretion to revise terms, so the Letter of Offer is the document to read closely. Check the lock-in period, the penalty for early redemption, the rate after the initial period and any conditions attached to subsidies.
How to choose between them
Use these questions as a short decision filter.
- Is your income simple and salaried? If yes, a direct application is workable. If you are self-employed, paid partly in commission, or buying with several commitments, a broker’s view across lenders is more useful.
- Do you have time? Collecting and comparing three written quotes takes effort. If your option fee clock or completion date is tight, a broker saves time.
- Is this a first purchase? First-time buyers benefit most from someone who explains the process, including how loan approval fits with the option to purchase.
- Is this a refinance? Compare your current bank’s repricing offer against external packages. A broker can show the alternatives, but your own bank may match them.
- Do you trust the fee explanation? Only proceed if the broker’s compensation is stated clearly and in writing.
A sensible hybrid also exists: get one quote from your own bank, ask a broker for the best alternative, and let the two compete. That gives you a benchmark whichever way you go.
Our perspective
We see mortgage planning as part of the purchase decision, not a step after it. The loan sets the price band, and the price band decides which homes are worth viewing. For that reason we encourage buyers to know their TDSR headroom before they book a viewing, not after they have fallen for a unit.
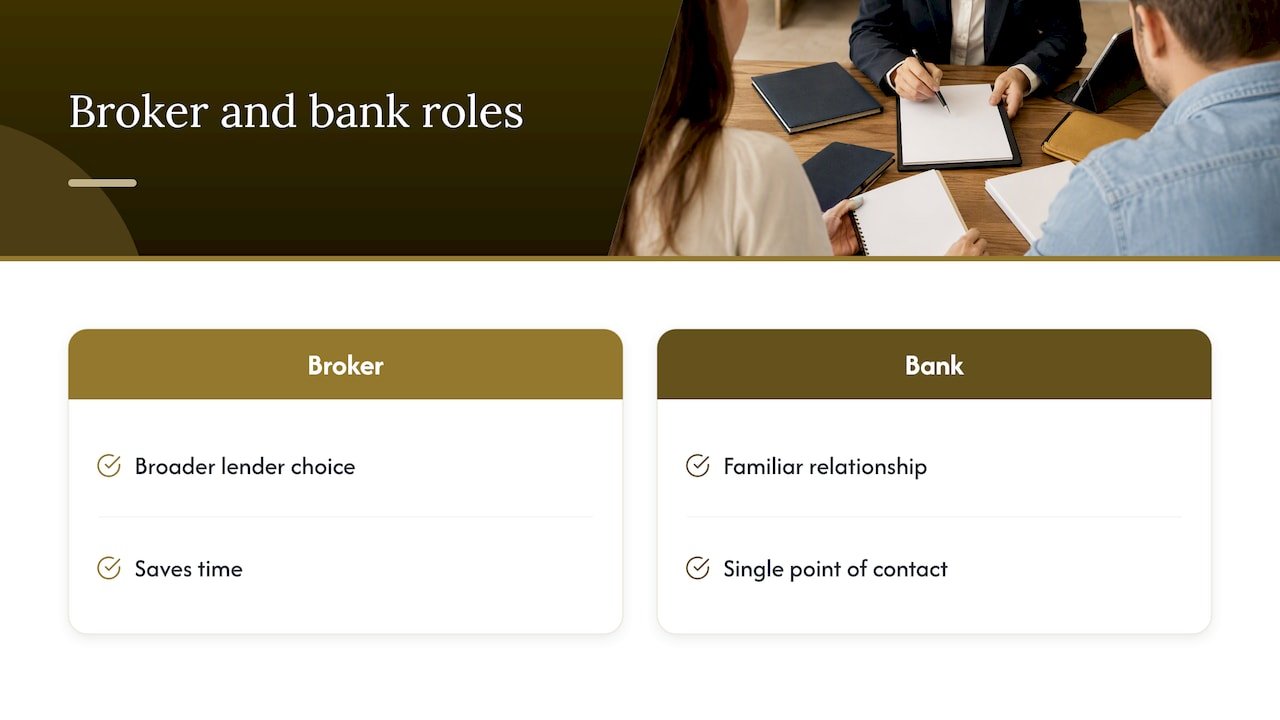
On broker versus bank, our view is practical. Neither is automatically better. A broker adds breadth and saves time, and a bank adds familiarity and a single point of contact. What matters is that the borrower understands the numbers: the rate after the initial period, the lock-in, the duty and the cash needed upfront. Where we work with buyers on investment properties and second purchases, loan structure often changes the outcome more than a small rate difference, as our breakdown of second property costs and sequencing shows.
We also advise caution about any promise that a lender can lend beyond MAS limits. The limits apply to everyone, and a plan that only works by stretching them is not a plan.
— Anderson
Plan the property side before the loan
A loan package is only useful if it fits the property you can actually buy. If you are still deciding what to buy, you can browse residential listings or commercial listings on Register Today. If you own a home and are weighing a sale or an upgrade, our free property valuation gives you a current figure to work from before you speak to any lender.
FAQ
Is it better to use a mortgage broker or go to the bank directly?
It depends on your profile and time. A broker compares packages across banks, which helps if your income is not straightforward or you are short of time. A direct application can work well if you have a strong relationship with one bank and are prepared to collect other quotes yourself.
Do mortgage brokers charge fees in Singapore?
Brokers are commonly paid by the bank through a referral fee when the loan is disbursed, so borrowers usually pay nothing directly. Specialised cases can differ, so ask for the fee arrangement in writing before you proceed.
Can a broker get me a bigger loan than a bank would?
No. The 55% TDSR and the LTV limits are set by MAS and apply to every financial institution, whichever channel you use. A broker can help you find a lender whose assessment of your income and package suits you, but not one that ignores the rules.
Does refinancing through a broker cost extra?
The broker’s service is generally paid by the bank, but refinancing has its own costs, including legal fees and potentially mortgage duty on the new mortgage. Work out the break-even point before you switch.
Sources
- MAS: Rules for New Housing Loans
- MAS: Residential Mortgage Pricing and Disclosure Practices
- IRAS: Mortgage Duty
- CPF Board: Home buying guide for members below 55
- Experian: What Is a Mortgage Broker?
- NerdWallet Canada: What Is a Mortgage Broker?
- Singapore mortgage broker guide (2026)
- Serviceability in property investment: what lenders assess